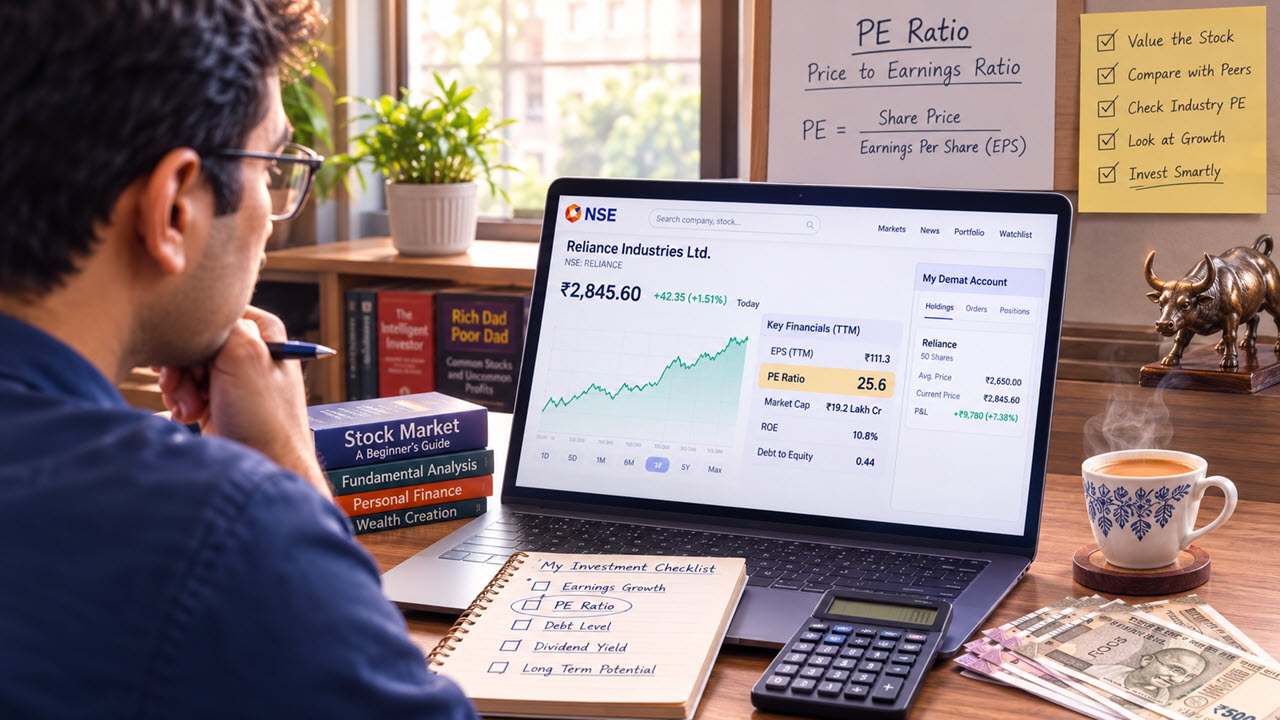
The price-to-earnings (P/E) ratio tells you how many rupees the market is paying for every rupee of a company’s annual profit. A P/E of 25 means investors are paying ₹25 for each ₹1 the company earned per share over the last year.
This guide covers the formula, trailing and forward P/E, where to look up the number, what the Nifty 50 P/E looks like today against its history, why sectors trade at very different multiples, and the situations where P/E gives the wrong signal. It ends with PEG, earnings yield and a worked comparison of two hypothetical companies.
The P/E formula
P/E = Market price per share ÷ Earnings per share (EPS)
EPS is net profit attributable to shareholders divided by the number of shares outstanding. You can also calculate P/E at the company level: market capitalisation ÷ net profit. Both give the same answer.
Suppose a share trades at ₹480 and the company earned ₹24 per share over the last four quarters. The P/E is 480 ÷ 24 = 20. If profits stayed flat forever and were all paid out, it would take 20 years of earnings to “pay back” the price.
Trailing P/E vs forward P/E
Trailing P/E (also called TTM, for trailing twelve months) uses the EPS of the last four reported quarters. It is based on actual, audited or reviewed numbers, so it is objective, but it looks backward.
Forward P/E uses estimated EPS for the next 12 months or the next financial year, usually an average of analyst forecasts. It reflects where the business is heading, but forecasts are often too optimistic, especially near market peaks.
If a company is growing, its forward P/E will be lower than its trailing P/E. A share at ₹480 with trailing EPS of ₹24 and expected EPS of ₹30 has a trailing P/E of 20 and a forward P/E of 16. A large gap between the two means the valuation depends heavily on that growth arriving.
Where to find a stock’s P/E
- NSE website (nseindia.com). A stock’s quote page shows its P/E next to the P/E of its sectoral index, which gives you an instant peer comparison. The “Indices” section of the market data page lists the P/E, price-to-book (P/B) and dividend yield of every Nifty index, updated daily.
- Screener tools. Free screeners such as Screener.in, Tickertape and Trendlyne show current P/E, historical P/E charts and median P/E over several years. You can also filter stocks by P/E range within an industry.
- Company results. For the most control, take EPS from the quarterly results filed with the exchange and calculate P/E yourself. This lets you strip out one-off gains, which ready-made figures usually include.
Different sites can show different P/Es for the same stock. The usual reasons are standalone vs consolidated EPS (consolidated includes subsidiaries), and trailing vs forward earnings. Check which one you are looking at before comparing.
Nifty 50 P/E: today vs history
NSE publishes a trailing P/E for the Nifty 50 every trading day. On 1 October 2026 it was 19.19, with a P/B of 2.75 and a dividend yield of 1.23% (source: NSE index data, as of 1 October 2026). The index closed at 22,421.95 that day, about 9.7% lower than a year earlier.
For context, the Nifty P/E has historically swung between the low teens and the high 30s. Year-end readings compiled by Forbes India show a low of about 12.7 at the end of 2008, after the global financial crisis, and a high of about 37.3 at the end of 2020, when earnings had collapsed during the pandemic while prices recovered. Data aggregators tracking NSE figures put the five-year median near 22 (as of October 2026).
One caution: until March 2021 NSE calculated index P/E on standalone earnings, and from April 2021 it switched to consolidated earnings. Consolidated profits are generally higher, so post-2021 P/Es read lower than the old series would have. Comparing today’s 19 directly with a 2019 or 2020 figure overstates how “cheap” the market is.
Index P/E is a useful temperature check, not a timing tool. Markets can stay expensive for years, and a low P/E during a slowdown can fall further if earnings drop. Our explainer on what counts as a stock market crash shows how quickly valuations can reset.
Why P/E differs so much by sector
A “good” P/E depends on the industry. Investors pay more for businesses with steady growth, high return on capital and little need for fresh investment. They pay less for businesses with volatile profits, heavy capital needs or government influence over pricing and dividends.
| Sector (Nifty index) | Index P/E on 1 Oct 2026 (NSE) | Why |
|---|---|---|
| FMCG (Nifty FMCG) | 30.4 | Stable demand, high return on capital, strong brands |
| IT (Nifty IT) | 17.8 | Asset-light and cash-rich, but tied to global tech spending |
| Private and large banks (Nifty Bank) | 12.9 | Profits depend on credit cycle; usually valued on P/B instead |
| PSU banks (Nifty PSU Bank) | 7.2 | History of bad loans, government ownership |
| Public sector companies (Nifty PSE) | 10.4 | Commodity and regulated businesses, high dividend payouts |
| Nifty 50 (whole market) | 19.2 | Blend of all sectors |
These are snapshots on one date, not fair-value bands. Sector P/Es move a lot over time; FMCG and IT, for example, have traded well above these levels in recent years. Always compare a stock with its own sector and its own history, not with the market as a whole.
When P/E misleads
Cyclical businesses
Steel, cement, metals, chemicals and auto companies earn far more at the top of their cycle than at the bottom. At the peak, profits are high and the P/E looks low, which is exactly when the stock may be most risky. At the bottom, profits are thin and P/E looks very high, which can be the better time to buy. For cyclicals, compare price with average earnings across a full cycle.
One-off gains and losses
A land sale, a tax write-back or a gain on selling a subsidiary can inflate EPS for one year and make the P/E look artificially low. A one-time write-off does the reverse. Look for “exceptional items” in the results and recalculate EPS without them.
Losses or tiny profits
If a company made a loss, P/E is negative and meaningless. If profit is very small, P/E can be 200 or more without telling you anything useful. For loss-making or early-stage companies, price-to-sales, cash burn and the path to profitability matter more.
High debt
P/E only looks at equity value. Two companies with the same P/E can carry very different risk if one has large borrowings. Debt also amplifies swings in EPS when interest rates or sales change. EV/EBITDA, which includes debt, is a better comparison for leveraged businesses. Our guide on how to tell if a stock is overvalued walks through it.
Two companions to P/E: PEG and earnings yield
PEG ratio
PEG = P/E ÷ expected annual EPS growth rate (in %). It adjusts P/E for growth. A company with a P/E of 30 growing EPS at 30% a year has a PEG of 1. One with a P/E of 15 growing at 5% has a PEG of 3, which is more expensive relative to its growth.
A PEG around 1 is often treated as reasonable and above 2 as stretched, but the result is only as good as the growth estimate. Use a growth rate you can justify from the company’s own history and guidance, not the most optimistic forecast.
Earnings yield
Earnings yield = EPS ÷ Price × 100, the inverse of P/E. A P/E of 20 is an earnings yield of 5%. This makes it easy to compare shares with bonds. With the Nifty 50 at a P/E of 19.19, its earnings yield is about 5.2%, while the 10-year government bond yield was about 7.21% (as of 1 October 2026, per Investing.com and Trading Economics).
Equity earnings are expected to grow while bond coupons are fixed, so shares normally yield less than bonds. But a very wide gap signals that the market is pricing in a lot of growth. Read more on how interest rates affect the stock market.
Worked example: comparing two hypothetical companies
Suppose you are comparing two fictional companies. Alpha Foods is a packaged food maker. Beta Engineering makes industrial equipment.
| Metric | Alpha Foods | Beta Engineering |
|---|---|---|
| Share price | ₹900 | ₹400 |
| Trailing EPS (reported) | ₹30 | ₹40 |
| Trailing P/E | 900 ÷ 30 = 30 | 400 ÷ 40 = 10 |
| Expected EPS growth | 20% a year | 5% a year |
| Expected EPS next year | 30 × 1.20 = ₹36 | 40 × 1.05 = ₹42 |
| Forward P/E | 900 ÷ 36 = 25 | 400 ÷ 42 = 9.5 |
| PEG (trailing P/E ÷ growth) | 30 ÷ 20 = 1.5 | 10 ÷ 5 = 2.0 |
| Earnings yield | 30 ÷ 900 = 3.3% | 40 ÷ 400 = 10% |
On P/E alone, Beta looks three times cheaper. On PEG, Alpha is cheaper relative to its growth (1.5 vs 2.0).
Now read the notes to Beta’s results. Suppose ₹12 of its ₹40 EPS came from a one-time sale of surplus land. Its recurring EPS is ₹28, so its true P/E is 400 ÷ 28 = 14.3 and its PEG becomes 14.3 ÷ 5 = 2.9. Suppose it also has borrowings equal to its entire equity, while Alpha is debt-free. Beta is no longer the obvious bargain.
None of this means Alpha is a buy. If its growth slows from 20% to 10%, its PEG rises to 3, and a P/E of 30 becomes hard to defend. The point is that P/E starts the analysis; growth, earnings quality and debt finish it.
How to use P/E: a quick checklist
- Confirm whether the P/E uses trailing or forward, standalone or consolidated EPS.
- Compare it with the company’s own 5-year median P/E.
- Compare it with direct peers and the sectoral index P/E.
- Remove exceptional items from EPS.
- Check growth (PEG) and debt (debt-to-equity, EV/EBITDA).
- For cyclicals, use average earnings across several years.
Common mistakes
- Treating low P/E as cheap. Many low-P/E stocks are low because profits are about to fall. This is the classic value trap, and it shows up often in penny stocks.
- Comparing across sectors. A bank at 12 and an FMCG company at 40 can both be fairly priced.
- Relying on one year’s earnings. One quarter or one year rarely represents a business.
- Ignoring the time horizon. Valuation matters most to long-term investors; short-term prices often ignore it.
FAQ
What is a good P/E ratio for Indian stocks?
There is no single number. A P/E is “good” only relative to the company’s growth, its own history and its sector. As a reference, the Nifty 50 traded at a P/E of 19.19 on 1 October 2026, but FMCG companies routinely trade above 30 and PSU banks below 10.
Is a high P/E always bad?
No. A high P/E can be justified if the company grows profits quickly and consistently, earns high returns on capital and needs little debt. It becomes a problem when growth slows, because the multiple usually falls along with the earnings estimates.
What is the difference between standalone and consolidated P/E?
Standalone P/E uses only the parent company’s profit. Consolidated P/E includes the profits of subsidiaries and joint ventures. For groups with large subsidiaries, consolidated figures give a fuller picture.
Can I use P/E for banks?
You can, but price-to-book (P/B) is more common for banks and NBFCs because their assets and equity are mostly financial and closely tied to book value. Pair P/B with return on equity and asset quality (gross and net NPA levels).
Does the Nifty P/E predict market returns?
It has a loose link with long-term returns: starting from lower valuations has historically led to better five-year returns on average. It is a poor short-term timing signal, because prices can move far from fair value for long periods.
Ramesh Iyer is the pen name of the founder and editor of StocksInfo.AI, an independent investor in Indian equities, mutual funds and ETFs since 2020. Every article is researched from primary sources such as SEBI, AMFI, NSE and the Income Tax Department, and fact-checked before publishing. About us