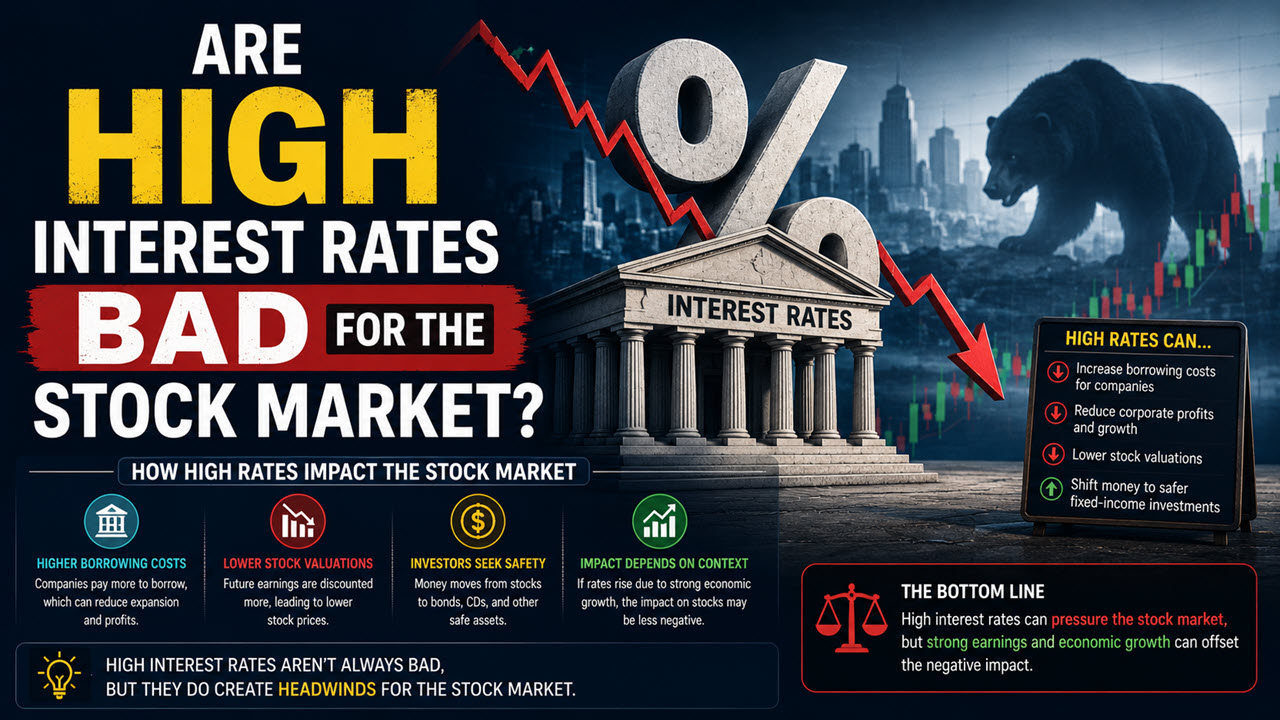
High interest rates are usually a headwind for stocks, because they raise borrowing costs, slow spending and make safe assets like bonds and fixed deposits more attractive. Rate cuts work the other way, but neither hikes nor cuts decide the market’s direction alone: the Nifty actually rose during the RBI’s 2022–23 hiking cycle, and it has fallen sharply in 2026 with rates unchanged.
This guide explains how the RBI repo rate reaches companies and households, why rates change what investors will pay for shares, which sectors react most, what happened in the last two rate cycles, how US Federal Reserve decisions spill into Indian markets, and what a long-term investor can sensibly do.
The repo rate and how it reaches you
The repo rate is the rate at which the Reserve Bank of India lends overnight money to banks against government securities. It is set by the six-member Monetary Policy Committee (MPC), which meets six times a year. As of early October 2026 the repo rate is 5.25%, unchanged for four meetings since December 2025, and the next decision is due on 7 October 2026.
A change in the repo rate passes through to the economy in steps. This pass-through is called transmission:
- Loans linked to an external benchmark. Since October 2019, banks have had to link new floating-rate retail and MSME loans to an external benchmark, usually the repo rate. These home and business loans reprice within a few months of an RBI move.
- Older MCLR-linked loans and deposits. These adjust more slowly. Fixed deposits reprice only when they are renewed or fresh money comes in.
- Bond markets. Government and corporate bond yields often move ahead of the RBI, because traders price expected changes in advance.
The 2025 cuts show how uneven this is. In his December 2025 statement, the RBI Governor said that after 100 basis points (1 percentage point) of cuts, banks’ weighted average lending rate on fresh rupee loans fell 69 basis points between February and October 2025, while fresh deposit rates fell 105 basis points. Borrowers got relief, and savers saw lower FD rates even faster.
Why interest rates change stock valuations
A share is a claim on a company’s future profits. To work out what those profits are worth today, investors discount them using a required return, called the discount rate. That rate starts from the risk-free return on government bonds and adds a premium for equity risk. When bond yields rise, the discount rate rises, and the same future profits are worth less today.
Worked example: a 1-point rise in the discount rate
Suppose a hypothetical company will earn ₹100 crore next year and investors expect its profits to grow 8% a year for a long time. A simple valuation formula is value = next year’s profit ÷ (required return − growth rate).
- At a 12% required return: ₹100 crore ÷ (0.12 − 0.08) = ₹100 crore ÷ 0.04 = ₹2,500 crore.
- If higher bond yields push the required return to 13%: ₹100 crore ÷ (0.13 − 0.08) = ₹100 crore ÷ 0.05 = ₹2,000 crore.
A one-point change in the discount rate cut the fair value by 20%, even though profits did not change. This is why high-growth stocks, whose profits lie further in the future, often fall hardest when rates rise. The same maths explains why a high P/E ratio is harder to justify when bond yields are high.
Earnings yield vs the 10-year G-sec yield
A quick way to compare stocks and bonds is the earnings yield, which is the P/E ratio turned upside down (1 ÷ P/E). As of 1 October 2026, the Nifty 50’s trailing P/E was about 19.2, which gives an earnings yield of roughly 5.2%. The 10-year government security (G-sec) yield was about 7.2% on the same date.
So bonds currently offer about 2 percentage points more than the index’s current earnings. Equity investors accept that gap because company profits can grow while a bond’s coupon is fixed. The wider the gap, the more earnings growth investors need to justify holding stocks, which is one reason rising bond yields pressure share prices. For a stock-level version of this check, see our guide on how to tell if a stock is overvalued.
Which sectors are most sensitive to rates
Rates do not hit every company equally. Debt levels, how customers pay (cash or loans) and where revenue comes from all matter.
| Sector | Why rates matter | When rates rise | When rates fall |
|---|---|---|---|
| Banks | Repo-linked loans reprice faster than deposits | Margins often widen at first; loan growth can slow later | Margins can narrow at first; credit demand usually picks up |
| NBFCs | Borrow from banks and bond markets to lend | Funding costs rise, margins squeezed | Cheaper funding; among the bigger beneficiaries |
| Real estate | Buyers depend on home loans; developers carry debt | Higher EMIs hurt demand; very sensitive | Affordability improves; often rallies on cuts |
| Autos | Most cars and many two-wheelers are bought on loan | Demand softens, especially entry-level | Supports demand along with income growth |
| IT services | Low debt; revenue mostly from US and Europe | Little direct effect from RBI; US rates and demand matter more | Little direct effect from RBI cuts |
| FMCG | Low debt, steady demand, but usually high P/E | Defensive on earnings, but valuations can compress | Modest benefit; rural demand and inflation matter more |
The bank row surprises many people. In 2022, a year of steady RBI hikes, the Nifty Bank index rose about 21%, helped by stronger loan growth and wider margins. Rate sensitivity is a starting point for research, not a rule.
The 2022–23 hiking cycle: 4.00% to 6.50%
With inflation rising after the Russia-Ukraine war began, the RBI raised the repo rate six times:
| Date | Change | Repo rate after |
|---|---|---|
| 4 May 2022 (unscheduled meeting) | +40 bps | 4.40% |
| 8 June 2022 | +50 bps | 4.90% |
| 5 August 2022 | +50 bps | 5.40% |
| 30 September 2022 | +50 bps | 5.90% |
| 7 December 2022 | +35 bps | 6.25% |
| 8 February 2023 | +25 bps | 6.50% |
How the Nifty did: the surprise May 2022 hike knocked the Nifty down 2.3% to 16,677.60 that day. By mid-June 2022 it had slipped below 15,500, as global sell-offs added to the pain. Yet it then recovered, ended 2022 at 18,105.30 (up 4.3% for the year), and traded above 17,800 on the day of the final hike in February 2023. Over the full cycle, the index was roughly 7% higher, despite a 250-basis-point rise in rates.
The lesson is that markets tend to react most when hikes are a surprise. Once a cycle is expected, earnings growth and flows take over.
The 2025 cutting cycle: 6.50% to 5.25%
After holding at 6.50% for two years, the RBI cut rates four times in 2025, a total of 125 basis points:
| Date | Change | Repo rate after |
|---|---|---|
| 7 February 2025 | −25 bps | 6.25% |
| 9 April 2025 | −25 bps | 6.00% |
| 6 June 2025 | −50 bps (plus a 100 bps CRR cut, phased) | 5.50% |
| 5 December 2025 | −25 bps | 5.25% |
How the Nifty did: it was trading around 23,600 on the day of the first cut. It sank to around 22,400 by 9 April 2025, when global tariff fears outweighed the cut. It then rallied to 26,186.45 on 5 December 2025, about 11% above the February level, and ended 2025 at 26,129.60, up 10.5% for the year. On the day of the December cut, the Nifty Realty index led the gains.
Where things stand in October 2026
Rate cuts did not protect the market in 2026. By 1 October 2026, the Nifty had fallen for eight straight weeks to 22,421.95, about 14% below its end-2025 close, with heavy foreign selling, Brent crude near $100 a barrel and the rupee past 96 to the dollar. The 10-year G-sec yield climbed above 7% in September. Economists polled ahead of the October meeting were debating whether the RBI’s next move would be a hike, the first since February 2023.
How the US Fed affects Indian stocks
Foreign portfolio investors (FPIs) own a large slice of India’s listed shares. When US interest rates rise, safe US Treasury bonds pay more and the dollar tends to strengthen, so some of that money leaves emerging markets like India. Selling by FPIs pushes down large-cap prices and weakens the rupee, which in turn raises imported inflation and makes the RBI’s job harder.
2022 is the clearest example. As the Fed raised rates seven times, FPIs pulled a record of about ₹1.21 lakh crore out of Indian equities that year. Steady buying by domestic mutual funds and SIP investors absorbed much of that selling, which helps explain why the Nifty still ended the year higher.
The same pattern is visible now. On 16 September 2026, the Fed raised its target range by 0.25 point to 3.75–4.00%, its first hike since 2023. The US 10-year Treasury yield rose above 5.3%, and FPIs had sold Indian shares worth roughly $27.8 billion in 2026 by the end of September. IT stocks have held up better, because their fortunes depend more on US demand than on rates in India.
What investors should do when rates change
Rate decisions are hard to predict and markets often price them in before they happen. These steps hold up whichever way rates move:
- Keep SIPs running. Rate-driven corrections let regular investments buy more units at lower prices.
- Stick to a target asset mix. Decide your equity-debt split in advance and rebalance once or twice a year. Our guide to asset allocation explains how.
- Use high rates for your debt portion. When yields are high, FDs, G-secs and short-duration debt funds lock in better returns. See whether bonds can cushion a stock market crash.
- Check debt before buying a stock. In a rising-rate period, look at the debt-to-equity ratio and interest coverage (operating profit ÷ interest cost). A coverage below 3 deserves a closer look.
- Review your loans. If you have a repo-linked home loan, a rise of 1 point adds noticeably to your EMI or tenure. Prepaying high-cost debt is a guaranteed return.
- Don’t chase “rate-cut stocks” after the news. Realty and NBFC stocks often move ahead of the cut, so buying on the announcement can mean buying the top.
Worked example: what a 2.5-point rise does to an EMI
Suppose Priya took a ₹40 lakh, 20-year home loan at 7.0%. Using the standard formula EMI = P × r × (1 + r)n ÷ ((1 + r)n − 1), with r = 7.0% ÷ 12 and n = 240 months, her EMI is about ₹31,012.
If her repo-linked rate rose by the same 2.5 points as the 2022–23 cycle, to 9.5%, the EMI would rise to about ₹37,285. That is ₹6,273 more each month, or about ₹75,000 a year that is no longer available for spending or investing. Multiply that across millions of households, and the effect on car, property and consumer spending becomes clear.
Common mistakes
- Selling all equity on a hike. In 2022–23, investors who exited after the first hike missed the recovery.
- Assuming cuts guarantee gains. 2026 shows that oil, the rupee and foreign flows can overwhelm the effect of lower rates.
- Ignoring the US. Fed decisions and US bond yields can matter as much as the RBI for large-cap Indian stocks.
- Putting long-term money in long-duration bonds to “bet” on cuts. If yields rise instead, long bonds fall in price. Match the bond fund’s duration to your time horizon.
A sharp fall driven by rates can feel like a crash. Our explainer on what counts as a stock market crash puts such moves in context.
FAQ
Do rate cuts always make the stock market go up?
No. Cuts lower borrowing costs and support valuations, but other forces can matter more. The Nifty fell to around 22,400 in April 2025, two months after the first cut, and dropped about 14% in 2026 even though the repo rate stayed at 5.25%.
What is the current RBI repo rate?
As of early October 2026 the repo rate is 5.25%, where it has been since 5 December 2025. The MPC’s next decision is due on 7 October 2026, so check the RBI website for the latest figure.
Which sectors benefit most from rate cuts?
Real estate, NBFCs and autos usually benefit most, because their customers or their own funding depend on loans. Banks get faster credit growth but can see margins narrow at first. IT and FMCG are less directly affected.
Why does the US Fed affect Indian stocks?
Higher US rates make US bonds more attractive and strengthen the dollar, so foreign investors often sell Indian shares. That selling can push down prices and the rupee, as in 2022 and again in 2026.
Should I move from equity funds to FDs when rates are high?
Not wholesale. High rates are a good time to fund the debt part of your plan at better yields, but switching everything means you risk missing the equity recovery. Base the split on your goals and time horizon, not on the rate cycle.
Are high rates good for debt mutual funds?
New money invested at high yields earns more. But when rates are rising, existing bond prices fall, so longer-duration funds can show losses for a while. Short-duration and money market funds are less affected.
Ramesh Iyer is the pen name of the founder and editor of StocksInfo.AI, an independent investor in Indian equities, mutual funds and ETFs since 2020. Every article is researched from primary sources such as SEBI, AMFI, NSE and the Income Tax Department, and fact-checked before publishing. About us