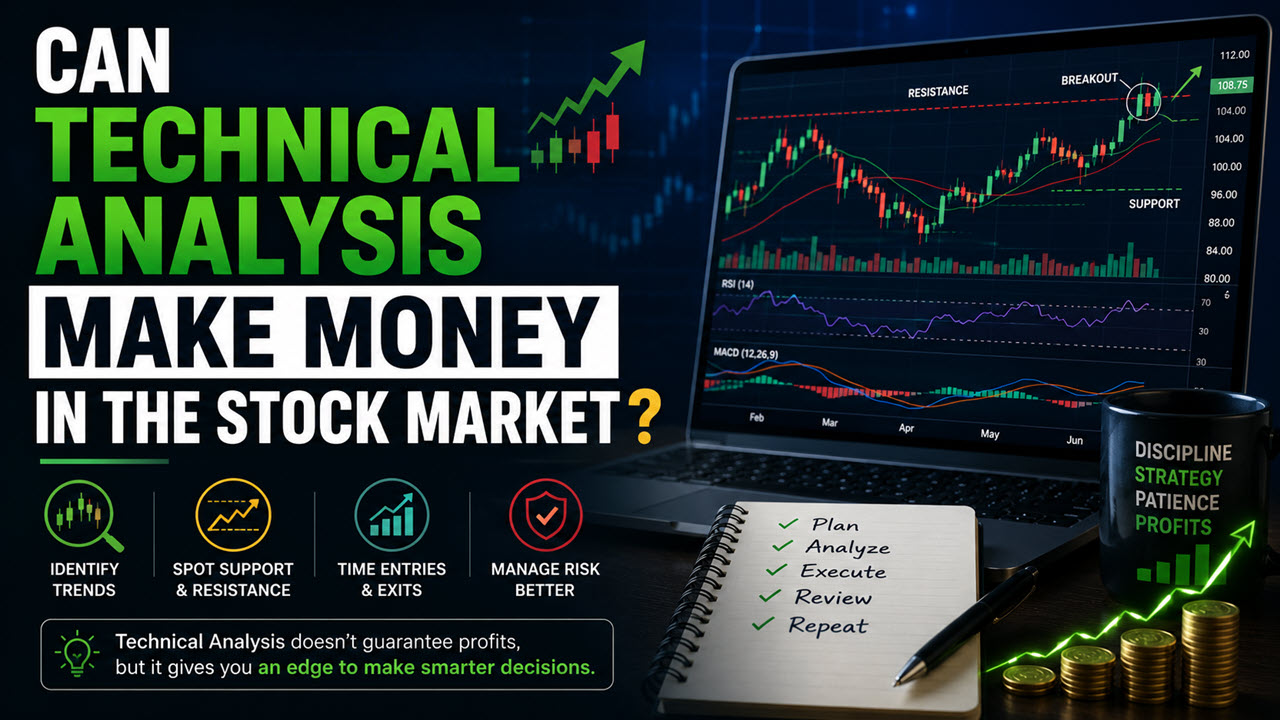
Technical analysis can make money for a small number of disciplined traders, but the evidence that it beats simply holding an index after costs and taxes is weak for most individuals. SEBI’s own data shows that most retail traders who trade frequently, the group that relies most on charts, lose money.
This article explains what technical analysis is and its main tools, what academic research has found, what SEBI’s studies say about Indian retail traders, and how to backtest a rule honestly. It includes a worked example of a moving-average rule after costs, a risk-management framework, a section on whether AI and ChatGPT tools help, and SEBI’s warnings about unregistered algo and tip sellers.
What technical analysis is
Technical analysis (TA) studies price and volume history to decide when to buy or sell. It assumes that prices reflect what traders collectively know and feel, and that patterns of supply and demand repeat often enough to give an edge. Fundamental analysis, by contrast, values the business itself through earnings, cash flow and ratios like the P/E ratio.
TA is mostly used for shorter holding periods, from minutes to a few months. Our comparison of trading vs investing explains why the two approaches suit different goals.
The core tools
| Tool | What it shows | How traders use it | Main weakness |
|---|---|---|---|
| Trend | Series of higher highs and higher lows (uptrend) or lower highs and lower lows (downtrend) | Trade in the direction of the trend | Trends are obvious only in hindsight |
| Support and resistance | Price zones where buying (support) or selling (resistance) has repeatedly appeared | Buy near support, sell near resistance, or trade breakouts | Zones are subjective; false breakouts are common |
| Moving averages | Average closing price over 20, 50 or 200 days | Price above the 200-day average is read as an uptrend; crossovers trigger signals | Lagging; many whipsaws in sideways markets |
| RSI | Relative Strength Index, a 0 to 100 score of recent gains vs losses (usually 14 periods) | Above 70 seen as overbought, below 30 as oversold | Can stay “overbought” for months in a strong trend |
| MACD | Moving Average Convergence Divergence: gap between a 12- and 26-period exponential average, plus a 9-period signal line | Crossovers of the signal line suggest momentum shifts | Lagging; signals often late |
| Volume | Number of shares traded | Breakouts on high volume are treated as more reliable | High volume can also mark the end of a move |
Candlestick patterns are another popular layer; our guide to candlestick patterns for swing trading covers the common ones.
What academic research says
The research is genuinely mixed, which is why both believers and sceptics can quote studies. The key question is not whether some rule made money in some period, but whether it keeps working on new data after realistic costs.
- Some early support. Brock, Lakonishok and LeBaron (1992) tested 26 simple moving-average and trading-range rules on about 90 years of Dow Jones data and found they had predictive power, before costs.
- The data-snooping problem. Sullivan, Timmermann and White (1999) expanded the test to thousands of rules on 100 years of data and adjusted for “data snooping”, the bias from testing many rules and reporting the winners. The best rules looked good in the original period, but their advantage did not hold up in the following decade.
- A review of reviews. Park and Irwin (2007) surveyed 95 modern studies: 56 found positive results, 20 negative and 19 mixed. They warned that many positive studies suffered from data snooping, ignored risk and understated transaction costs, and that profits had tended to fade in more recent data.
- Costs eat the edge. In Barber, Lee, Liu and Odean’s study of day traders in Taiwan, heavy day traders earned gross profits that were not enough to cover their transaction costs, and more than eight in ten day traders lost money in a typical six-month period. A small group showed persistent skill.
A fair summary: simple trend-following signals have sometimes shown small edges, especially in less efficient markets and earlier decades, but those edges are thin, unstable and easily wiped out by brokerage, taxes and slippage (the gap between the price you expect and the price you get).
What SEBI data says about Indian retail traders
SEBI does not study technical analysis as such, but it has studied the people most likely to use it: active intraday and derivatives traders.
- Intraday cash segment (July 2024 study): more than 70% of individual intraday traders lost money in FY23. Among those making over 500 trades a year, 80% lost money. Loss-makers spent an extra 57% of their trading losses on trading costs.
- Equity F&O (September 2024 study): 93% of individual traders lost money between FY22 and FY24, with aggregate losses above ₹1.8 lakh crore.
- Equity F&O (FY26 study, August 2026): 87.7% of individual traders still lost money, despite tighter rules and fewer participants.
The pattern across studies is that the more often people trade, the more likely they are to lose. Our articles on intraday trading and options trading go deeper into these numbers.
How to backtest a strategy honestly
A backtest runs a trading rule on historical data to see how it would have done. Almost any rule can be made to look brilliant on past data, so the value of a backtest depends on how strictly it is done.
- Write the rule before looking at results. Entry, exit, stop-loss and position size must be precise enough that a computer could follow them.
- Split the data. Build and tune the rule on one period (in-sample), then test it once on a later period it has never seen (out-of-sample). If it fails out-of-sample, do not keep tweaking until it passes.
- Avoid overfitting. A rule with many tuned parameters (a 17-day average, RSI 63, exit after 4 days) usually fits past noise. Fewer parameters, and results that hold across nearby values, are more trustworthy.
- Include every cost. Brokerage, STT, exchange charges, stamp duty, GST, DP charges and slippage. For delivery trades in shares, STT alone is 0.1% on both the buy and the sell.
- Include tax. Gains on listed shares held 12 months or less are short-term and taxed at 20%; intraday profits are treated as speculative business income at your slab rate.
- Avoid look-ahead and survivorship bias. Use only information available at the time of each trade, and include stocks that were later delisted, not just today’s winners.
- Compare with buy-and-hold. The benchmark is a cheap index fund, not zero. Also look at the worst drawdown (largest peak-to-trough fall), not just the return.
- Paper trade, then trade small. Run the rule live with little or no money for a few months to see if real fills match the backtest.
Worked example: a moving-average rule after costs
Suppose Rohan backtests a rule on a large, liquid stock: buy when the price closes above its 200-day moving average, sell when it closes below. All figures are hypothetical, chosen to show how costs and tax change the result.
- Capital: ₹5 lakh.
- The backtest shows a gross return of 12% a year, against 11% a year for simply holding the stock.
- The rule averages six round trips (a buy and a sell) a year, because prices cross the average often in sideways markets.
- Assumed cost per round trip: 0.3% of the trade value (0.2% STT, plus brokerage, exchange charges, stamp duty, GST, DP charges and slippage).
| Step | Moving-average rule | Buy and hold |
|---|---|---|
| Gross gain in a year | 12% × ₹5,00,000 = ₹60,000 | 11% × ₹5,00,000 = ₹55,000 |
| Trading costs | 6 × 0.3% × ₹5,00,000 = ₹9,000 | About ₹0 (no trades during the year) |
| Gain before tax | ₹51,000 | ₹55,000 |
| Tax | Short-term gains at 20%: about ₹10,200 | Nil until sold; if sold after 12 months, gains up to ₹1.25 lakh a year are tax-free, then 12.5% |
| Gain after tax | About ₹40,800 (8.2%) | ₹55,000 (11%) |
A rule that looked one percentage point better on paper ends up nearly three points worse. The tax figure is simplified: STT cannot be deducted when calculating capital gains, so the real tax would be slightly higher. To be worth the effort, the rule would need to beat buy-and-hold by well over 2.5 percentage points a year, out-of-sample, every year.
The one real benefit trend rules can offer is smaller drawdowns, because they move to cash during long falls. Some investors accept lower returns for that. But in choppy markets, the same rule can produce a string of small losses.
Risk management matters more than signals
Traders who survive tend to focus on how much they can lose per trade, not on finding perfect entries. Three ideas do most of the work.
Position sizing with a fixed risk per trade
Many traders risk no more than 1% of capital on a single trade. With ₹5 lakh, that is ₹5,000. If Rohan buys at ₹500 with a stop-loss at ₹475, his risk is ₹25 a share, so he buys ₹5,000 ÷ ₹25 = 200 shares, a ₹1 lakh position. Ten losses in a row would cost about 10% of capital, which is painful but survivable.
Expectancy, after costs
Expectancy is the average amount you make per trade. Suppose Rohan wins 40% of trades with an average gain of ₹9,000, and loses 60% with an average loss of ₹5,000. Expectancy = (0.40 × ₹9,000) − (0.60 × ₹5,000) = ₹3,600 − ₹3,000 = ₹600 per trade.
Now add costs of 0.3% on each ₹1 lakh round trip, or ₹300. His edge halves to ₹300 per trade, before tax. A small drop in win rate, say to 37%, would make it negative: (0.37 × ₹9,000) − (0.63 × ₹5,000) − ₹300 = ₹3,330 − ₹3,150 − ₹300 = −₹120.
Rules that keep you in the game
- Place the stop-loss when you enter, and do not widen it after entry.
- Set a daily or monthly loss limit (for example 3% of capital a month) and stop trading when it is hit.
- Avoid leverage until you have a long, profitable record with real money.
- Keep a trading journal with entry, exit, reason and result, and review it monthly.
- Keep trading capital separate from long-term savings, which are better kept in diversified funds.
Do AI and ChatGPT tools help?
AI chatbots can be useful assistants, but they do not solve the core problem of finding an edge that survives costs. Used carefully, they can:
- Explain indicators and concepts in plain language.
- Help write backtesting code, which you must then check line by line.
- Summarise long documents such as annual reports or SEBI circulars, with the original kept at hand.
The limits are serious. General chatbots may not have live market data, can state wrong prices or rules with confidence, and cannot know the future any better than anyone else. AI-written backtest code often contains look-ahead bias or ignores costs, which produces results that look excellent and are meaningless. A chatbot is also not registered with SEBI, so its “stock picks” are not regulated advice and carry no accountability.
Be especially wary of apps and channels selling “AI-powered” signals. If a model reliably made money, its owners would have little reason to sell it for a monthly fee.
SEBI’s warnings on algo sellers and tip providers
SEBI has repeatedly acted against people selling trading strategies and tips outside the rules.
- No return claims for algos (September 2022): SEBI noted that unregulated platforms were marketing algo strategies with claims of high returns. Its circular of 2 September 2022 barred stockbrokers from referring to the past or expected performance of an algorithm, or associating with platforms that do.
- Retail algo framework (February 2025): SEBI’s circular on safer retail participation in algorithmic trading requires algos run through broker APIs to be approved by the exchange and tagged with an identifier. Providers of “black-box” algos, whose logic is not disclosed to the user, must register with SEBI as research analysts. The framework was phased in, with brokers required to comply in full by April 2026.
- No ties with unregistered finfluencers (August 2024): SEBI barred regulated entities, including brokers, from associating with unregistered people who give securities advice or make claims about returns.
- Assured returns are a red flag: SEBI has cautioned investors against unregistered entities promising assured or very high returns, some of which show fake SEBI certificates.
Before paying for any tips, course “signals” or strategy, check that the person or firm appears in SEBI’s list of registered research analysts or investment advisers on the SEBI website. More warning signs are covered in our guide on how to avoid losing money in the stock market.
Common mistakes
- Stacking many indicators that all measure the same thing (RSI, stochastics and MACD are all momentum).
- Judging a strategy on a few winning trades instead of 100 or more.
- Trading illiquid small-caps, where wide bid-ask spreads and slippage destroy small edges.
- Moving from cash trades to options to “speed up” results, which adds leverage and time decay.
- Ignoring taxes and the ITR filing that frequent trading requires.
FAQ
Is technical analysis better than fundamental analysis?
They answer different questions. Fundamental analysis asks what a business is worth; technical analysis asks when to trade. Long-term investors rely mainly on fundamentals, and some use charts only to time entries.
Which indicator is the most accurate?
None is reliably accurate on its own. Moving averages, RSI and MACD are all derived from past prices, so they describe what has happened rather than predict what will. Risk management and costs matter more than the choice of indicator.
How long does it take to learn technical analysis?
The basics take a few weeks. Knowing whether you have a profitable method takes far longer, because you need a large number of trades, ideally a year or more of small live trades, to separate skill from luck.
Can I trust ChatGPT for stock tips?
No. Chatbots can be wrong about facts and prices, have no special insight into future prices, and are not SEBI-registered advisers. Use them for learning and checking your reasoning, not for buy or sell decisions.
Is paid algo trading software legal in India?
Algo trading is legal through brokers that follow SEBI’s framework, using exchange-approved algos. Black-box strategy providers must be registered as research analysts, and no regulated broker may advertise an algo’s past or expected returns.
Ramesh Iyer is the pen name of the founder and editor of StocksInfo.AI, an independent investor in Indian equities, mutual funds and ETFs since 2020. Every article is researched from primary sources such as SEBI, AMFI, NSE and the Income Tax Department, and fact-checked before publishing. About us