Yes, some people make money trading options, but very few individuals do. SEBI’s own studies show that between 88% and 93% of individual traders in equity futures and options (F&O) lost money in every period it has examined, and most of those losses come from options.
This article sets out what SEBI found, how call and put options work using a Nifty example with today’s lot size, why buyers and sellers face very different risks, what the 2024-25 rule changes did, how F&O profits are taxed, and a checklist for anyone who still wants to learn.
What SEBI’s studies found
SEBI has published several studies of individual traders in the equity derivatives segment. Each one used trade data from the largest brokers, so these are not surveys or opinions. The pattern has barely changed in four years.
| SEBI study (released) | Period covered | Individuals who lost money | Key loss figures |
|---|---|---|---|
| January 2023 | FY22 | 89% | Only about 11% of individual traders made a profit |
| September 2024 | FY22 to FY24 | 93% | Aggregate losses above ₹1.8 lakh crore; average loss about ₹2 lakh per trader including costs |
| July 2025 | FY25 | About 91% | Net losses widened about 41% to roughly ₹1.06 lakh crore (later revised to about ₹1.12 lakh crore) |
| August 2026 | FY26 | 87.7% | Net losses of ₹91,685 crore; average loss about ₹1.17 lakh per person |
A few details from the September 2024 study stand out. Only about 1% of individual traders earned more than ₹1 lakh over three years after costs. Individuals spent around ₹50,000 crore on transaction costs in those three years, while proprietary traders and foreign portfolio investors as a group booked large trading profits in FY24. In other words, the money retail traders lose largely ends up with better-equipped professionals.
The FY26 study, released in August 2026, shows fewer people trading after the new rules: active individual traders fell about 18% to 87.5 lakh and new entrants fell about 40%. But the share of loss-makers is still close to nine in ten, and the average loss per person actually rose slightly. SEBI also found that about three-quarters of individual traders had annual incomes below ₹5 lakh, and traders under 30 made up 43% of the base. If you want the broader comparison between this kind of activity and long-term investing, see our guide to trading vs investing.
How call and put options work
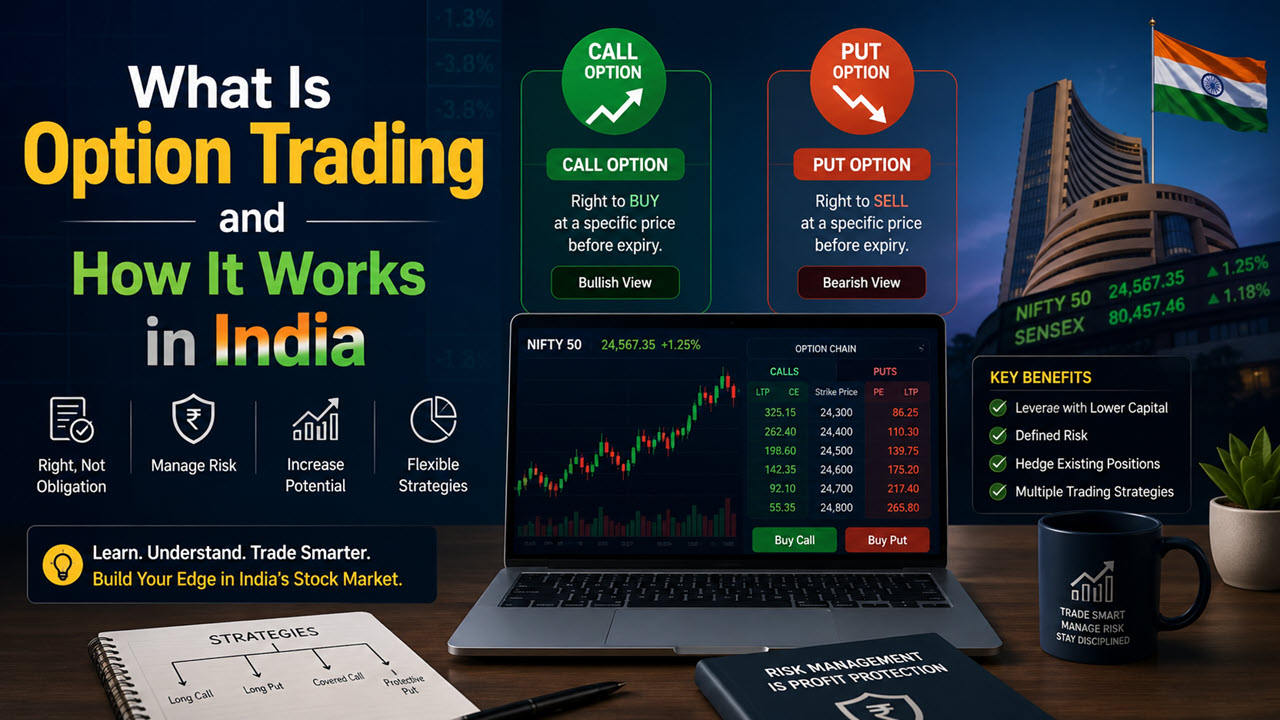
An option is a contract that gives the buyer a right, but not an obligation, to buy or sell an underlying asset at a fixed price (the strike price) on or before expiry. The buyer pays a price for this right, called the premium. The seller (also called the writer) receives the premium and takes on the obligation.
- Call option (CE): gains value when the underlying rises above the strike price. You buy a call if you expect a rise.
- Put option (PE): gains value when the underlying falls below the strike price. You buy a put if you expect a fall.
- Lot size: options trade in fixed lots. The Nifty 50 lot size is 65 units, effective from the January 2026 contracts (as of October 2026, per NSE’s revision). It was 75 before that.
- Index options are cash-settled: no shares change hands. At expiry, you receive or pay the difference in cash.
Worked example: buying a Nifty call
The prices here are hypothetical and chosen to keep the maths simple. Suppose Nifty is at 25,000 and Rahul buys one lot of the 25,100 call expiring in seven days at a premium of ₹120.
- Cost: ₹120 × 65 = ₹7,800, paid upfront. This is also his maximum loss, before charges.
- Breakeven at expiry: strike + premium = 25,100 + 120 = 25,220. Nifty must close above this for him to make money, and a little higher to cover charges.
- If Nifty expires at 25,400: the option is worth 25,400 − 25,100 = 300 points. Value = 300 × 65 = ₹19,500. Profit = ₹19,500 − ₹7,800 = ₹11,700 before charges.
- If Nifty expires at 25,150: the option is worth 50 points, or ₹3,250. Loss = ₹7,800 − ₹3,250 = ₹4,550. Nifty went up, and he still lost money.
- If Nifty expires at or below 25,100: the option expires worthless. Loss = ₹7,800.
Now add time decay (theta), the steady fall in an option’s value as expiry approaches. Suppose Nifty stays flat at 25,000 for three days and the premium slips from ₹120 to ₹70. Rahul has lost (120 − 70) × 65 = ₹3,250, or about 42% of his money, without the market moving against him at all. Decay speeds up in the final days, which is why cheap, short-dated options so often go to zero.
A put works the same way in reverse. If Rahul instead bought the 24,900 put at ₹110, his cost would be ₹110 × 65 = ₹7,150 and his breakeven at expiry would be 24,900 − 110 = 24,790.
Note that the contract value here is 25,000 × 65 = ₹16.25 lakh. That is deliberate: SEBI now requires index derivative contracts to be worth at least ₹15 lakh when introduced.
Option buyer vs option seller: who carries what risk
The buyer’s loss is capped at the premium. The seller’s profit is capped at the premium, but the loss is not. Using the same example, suppose someone sold that 25,100 call at ₹120 and collected ₹7,800. If Nifty jumps to 25,600 by expiry, the call is worth 500 points, and the seller loses (500 − 120) × 65 = ₹24,700, more than three times what they collected.
| Feature | Option buyer | Option seller (writer) |
|---|---|---|
| Upfront payment | Full premium | Margin, usually many times the premium received |
| Maximum profit | Large in theory | Limited to premium received |
| Maximum loss | Premium paid plus charges | Unlimited on a naked (unhedged) call; very large on a naked put |
| Time decay | Works against you | Works for you |
| Typical outcome | Many small losses, occasional large wins | Many small wins, occasional large losses |
Selling looks attractive because it wins more often, but one sharp gap on a news day can wipe out months of small gains. SEBI’s FY26 study found about 92% of individual losses came from options, and around 97% of traders mainly bought options, so the typical retail trader is on the side where decay works against them.
SEBI’s 2024-25 rule changes
After the September 2024 study, SEBI issued a circular on 1 October 2024 to cool speculation in index derivatives. The measures came into force in stages:
| Measure | What changed | Effective from |
|---|---|---|
| Bigger contract size | Minimum contract value raised from ₹5–10 lakh to ₹15 lakh at introduction | 20 November 2024 |
| One weekly expiry per exchange | Each exchange may offer weekly expiry on only one benchmark index | 20 November 2024 |
| Extra margin on expiry day | Additional 2% extreme loss margin on short options expiring that day | 20 November 2024 |
| Upfront premium | Brokers must collect the full option premium from buyers upfront | 1 February 2025 |
| No calendar-spread benefit on expiry day | Margin offset for positions across expiries removed on the expiry day | 1 February 2025 |
| Intraday position monitoring | Exchanges check position limits during the day, with at least four random snapshots | 1 April 2025 |
In 2025, SEBI also fixed the expiry days so the two exchanges no longer compete for the same day. From September 2025, NSE’s weekly Nifty contracts expire on Tuesdays and BSE’s weekly Sensex contracts expire on Thursdays. Separately, Budget 2026 raised securities transaction tax (STT) on options from 0.1% to 0.15% of the premium on sale, effective 1 April 2026, which makes frequent trading costlier.
How F&O income is taxed
Profits from F&O on a recognised exchange are treated as non-speculative business income, not capital gains. They are added to your other income and taxed at your slab rate. You file ITR-3 and can deduct genuine trading expenses such as brokerage, internet and advisory software.
- Losses: an F&O loss can be set off against other income except salary in the same year. Any balance can be carried forward for up to 8 years against business income, but only if you file your return by the due date.
- Turnover is not contract value: under the ICAI guidance note, F&O turnover is the sum of the absolute profit or loss on each trade. A ₹5,000 profit on one trade and a ₹3,000 loss on another add up to ₹8,000 of turnover.
- Tax audit thresholds: an audit is required if turnover exceeds ₹1 crore, or ₹10 crore where cash receipts and cash payments are each within 5% of the total. Since F&O is settled through banks, most traders fall under the ₹10 crore limit. These limits sit in section 63 of the Income-tax Act, 2025 (section 44AB of the old Act).
- Presumptive-scheme trap: traders who used the presumptive scheme in an earlier year and later declare lower profits or a loss can still need an audit. Check this with a chartered accountant before filing.
From 1 April 2026, the Income-tax Act, 2025 replaced the 1961 Act. The section numbers changed, but the treatment of F&O income and the audit thresholds carried over.
If you still want to learn: a risk checklist
- Use only money you can lose completely. Keep it separate from your emergency fund and long-term investments.
- Paper-trade first. Track hypothetical trades for at least two or three months, including charges, before risking real money.
- Cap risk per trade. A common rule is to risk no more than 1–2% of trading capital on any single trade.
- Never sell naked options as a beginner. If you sell, hedge with a further out-of-the-money option so your maximum loss is known.
- Avoid expiry-day lottery tickets. Cheap options on expiry day decay to zero far more often than they pay off.
- Know your breakeven before you click buy. Include STT, exchange charges, brokerage and GST.
- Keep a trade journal. Record why you entered, where you exited and what you learned. Review it monthly.
- Set a stop-the-experiment rule. For example, stop if you lose 25% of your trading capital, and reassess.
- Ignore tips and paid “sure-shot” calls. Anyone giving specific trade advice for a fee must be SEBI-registered; check the registration number on SEBI’s website.
Many traders lean on chart patterns to time entries. Read whether technical analysis can make money before relying on it, and see our guide on how to avoid losing money in the stock market.
Common mistakes
- Buying far out-of-the-money options because they are cheap. A low premium usually reflects a low chance of paying off.
- Averaging down on a losing option. Time decay keeps working against the whole position.
- Ignoring implied volatility. Premiums often drop sharply after an event such as an RBI policy or a budget, even if the market moves your way.
- Overtrading. Every round trip costs money, and SEBI found transaction costs alone turned many small winners into net losers.
- Not filing returns for loss years. Without a timely return you lose the right to carry the loss forward.
For most people, steady investing does far more for long-term wealth than trading. Our explainer on the power of compounding shows why time in the market tends to beat timing it.
FAQ
What percentage of option traders lose money in India?
SEBI’s studies put the share of loss-making individual F&O traders at 89% for FY22, 93% across FY22 to FY24, about 91% in FY25 and 87.7% in FY26. Most of those losses came from options rather than futures.
What is the Nifty lot size now?
The Nifty 50 lot size is 65 units, effective from the January 2026 contract series (as of October 2026). NSE reviews lot sizes periodically, so check NSE’s latest circular before you trade.
How much money do I need to start options trading?
To buy an option, you need the full premium for one lot, which can be a few thousand rupees for a Nifty option. Selling needs margin that is usually many times larger. The more useful question is how much you can afford to lose completely.
Is options trading income taxed as capital gains?
No. F&O income is non-speculative business income taxed at your slab rate, and you file ITR-3. Losses can be carried forward for 8 years if you file on time.
Is option selling safer than option buying?
Sellers win more often, but a naked call has unlimited risk, and a single large move can erase many months of gains. Selling is only manageable with hedges, strict position sizing and enough capital to absorb a shock.
Ramesh Iyer is the pen name of the founder and editor of StocksInfo.AI, an independent investor in Indian equities, mutual funds and ETFs since 2020. Every article is researched from primary sources such as SEBI, AMFI, NSE and the Income Tax Department, and fact-checked before publishing. About us