
Most salaried Indians start investing with the same mix of excitement and confusion. You open a Demat account, hear friends discuss a hot stock on the NSE or BSE, see social-media posts about multibagger returns, and wonder whether a ₹5,000 SIP can really help fund your child’s education or retirement.
I have seen this journey many times, including my own early mistakes. Good investing is not about finding the next stock that doubles in three months. It is about building a simple system, investing regularly, avoiding expensive mistakes, and giving your money enough time to grow.
This step-by-step guide will show you how to be a good investor in the stock market without turning investing into a daily guessing game.
How to Be a Good Investor: Start With Clear Goals
The first rule of becoming a good investor is simple: know why you are investing. Money without a purpose often gets moved around whenever markets become noisy.
Your goals can include buying a house, creating a retirement corpus, funding your child’s higher education, building financial independence, or simply protecting savings from inflation. Each goal needs a different time horizon and risk level.
For example, consider Suresh, a 30-year-old salaried professional earning ₹75,000 per month. He wants to build wealth for retirement, which is at least 25 years away. He can take more equity exposure because he has time to recover from market corrections. But if he wants money for a house down payment in three years, he should not put that amount into small-cap stocks.
A good investor separates money into buckets:
- Emergency fund: Usually six to twelve months of essential expenses, kept in safe and easily accessible options.
- Short-term goals: Money needed within three years, where capital protection matters more than high returns.
- Long-term goals: Money meant for seven years or more, where equity, mutual funds, and ETFs may play a larger role.
- Learning capital: A small amount for studying direct stocks, if you want hands-on experience.
Starting early makes a major difference because money earns returns, and then those returns begin earning returns. This is the real benefit of starting your investment journey early and using the power of compounding patiently.
Build the Right Investing Foundation
Before buying your first stock, understand the basic tools and products. Many beginners lose money because they start trading before they understand what they own.
A Demat account is a digital account that holds shares, ETFs, and other securities in electronic form. Think of it as a digital locker for your investments.
A trading account lets you place buy and sell orders on exchanges such as the NSE and BSE. Your trading account connects your bank account, Demat account, and stock exchange transactions.
A mutual fund pools money from many investors and invests it in shares, bonds, or other assets. A fund manager manages active mutual funds, while an index fund simply aims to track an index such as the Nifty 50.
An ETF, or exchange-traded fund, also tracks an index, sector, commodity, or asset class. You buy and sell an ETF on the stock exchange just like an ordinary share. If you are unsure which route suits you, this guide on ETF vs mutual fund investing can help you understand the practical differences.
For a beginner like Suresh, a simple starting structure may look like this:
| Monthly amount | Product type | Purpose |
|---|---|---|
| ₹5,000 | Index fund SIP | Core long-term equity exposure |
| ₹2,000 | Large-cap or flexi-cap mutual fund | Diversified growth |
| ₹2,000 | Debt fund or safe savings bucket | Stability and short-term needs |
| ₹1,000 | Direct stocks or ETF | Learning and controlled experimentation |
This is only an illustration, not a fixed portfolio formula. Your allocation should match your income, goals, emergency savings, and comfort with market falls.
Pro Tip: I have found that investors make better decisions when their first portfolio looks boring. A simple index fund and regular SIP often beat a complicated portfolio of tips, penny stocks, and random thematic funds.
How to Be a Good Investor With SIP Discipline
A SIP, or Systematic Investment Plan, means investing a fixed amount in a mutual fund at regular intervals, usually every month. Instead of trying to predict the best day to invest, you invest through good markets, bad markets, rallies, and corrections.
When you invest ₹5,000 every month, you buy more mutual fund units when the NAV is lower and fewer units when the NAV is higher. NAV, or Net Asset Value, is the per-unit price of a mutual fund.
Suppose Suresh invests ₹5,000 monthly for 20 years. If his investments earn an average annual return of 12 percent, his total contribution would be ₹12 lakh. The potential corpus could grow to roughly ₹50 lakh, depending on actual market returns and fund performance.
The point is not that markets will deliver exactly 12 percent every year. They will not. Some years will be negative, while other years may produce strong gains. The key lesson is that consistent investing gives compounding time to work.
A SIP helps salaried investors because it fits naturally with monthly cash flow. Set the SIP date soon after your salary arrives, not at month-end when other expenses have already consumed the money. You can also use a SIP calculator to estimate how different monthly amounts and time periods could affect your long-term goal.
As income rises, increase the SIP amount. If Suresh raises his ₹5,000 SIP by 10 percent each year, he can potentially create a much larger corpus than by keeping the contribution flat for decades.
Choose Products You Understand
Good investors do not buy every product they hear about. They understand the product, its risks, and its role in the portfolio before investing.
For most beginners, index funds, diversified equity mutual funds, and broad-market ETFs offer a sensible starting point. They spread money across many companies, reducing the impact of one company performing badly.
Start With Diversification
Diversification means spreading your money across different companies, sectors, and asset types. It reduces the risk of a single wrong decision damaging your entire portfolio.
If you invest all your money in one small-cap stock because someone called it the “next multibagger,” you are taking concentrated risk. The company may perform well, but it can also face poor results, debt issues, management problems, or a sharp price decline.
A diversified portfolio may include:
- Large-cap funds: Companies with large market value and generally established businesses.
- Mid-cap funds: Medium-sized companies with stronger growth potential but higher volatility.
- Small-cap funds: Smaller companies that may grow faster but can fall sharply during weak markets.
- Debt funds: Funds that invest in fixed-income securities and can provide stability, although they also carry risks.
- ETFs: Exchange-traded funds that provide low-cost market, sector, gold, or other asset exposure.
Before adding a fund, learn how it fits into your existing investments. Do not buy five mutual funds that all own mostly the same large companies. You can explore ETF investing tips and the benefits of ETF investing if you want a low-cost, exchange-traded route.
Treat Direct Stocks as Research Work
Direct equity investing can build wealth, but it requires effort. When you buy a share, you become a part-owner of a business. You need to understand how that business earns money, whether it has manageable debt, how it compares with competitors, and whether its valuation makes sense.
One useful starting metric is the P/E ratio, or price-to-earnings ratio. It compares a company’s share price with its earnings per share. A high P/E does not automatically mean a stock is expensive, and a low P/E does not automatically mean it is cheap. Growth, business quality, debt, industry conditions, and management quality all matter.
Learn the basics of how to use the P/E ratio and how to identify an overvalued stock before buying before putting serious money into individual shares.
A practical beginner approach is to keep direct stocks limited to 10–20 percent of your equity allocation until you gain experience. Let diversified mutual funds or index funds form the core of your portfolio.
Focus on Long-Term Investing, Not Daily Noise
The stock market moves every day, but your financial goals do not. A good investor learns to separate market noise from meaningful business changes.
News channels, social media, and WhatsApp groups reward urgency. They make every market move sound like a once-in-a-lifetime opportunity or disaster. But wealth usually comes from owning quality assets for years, not from reacting to every headline.
Long-term investing means buying assets with a time horizon of at least five to seven years. It gives businesses time to grow earnings and gives you a better chance to recover from market corrections.
For example, if Suresh invests ₹10,000 monthly and the market falls 15 percent after six months, he should not automatically stop his SIP. His new investments may buy more units at lower NAVs. If his goals remain long term and his emergency fund is secure, continuing the plan may make more sense than selling in panic.
Market corrections are uncomfortable, but they are normal. Read about taking advantage of a stock market correction and understand why stock market crashes happen before deciding how you will respond.
Pro Tip: In my experience, people rarely lose money because they missed one perfect buying day. They lose money because they buy during excitement, sell during fear, and repeat that cycle for years.
Review Your Portfolio Without Over-Trading
Good investing needs regular review, but it does not need constant action. Checking your portfolio every hour can push you toward unnecessary buying and selling.
Review your investments once or twice a year. During that review, ask practical questions:
- Has my goal or time horizon changed?
- Has my income increased enough to raise my SIP?
- Is one asset class now much larger than I intended?
- Does a stock’s business case still hold?
- Am I holding a fund or stock only because I do not want to accept a loss?
Rebalancing means bringing your portfolio back to its planned allocation. For instance, if equity rises sharply and becomes 80 percent of your portfolio instead of your intended 70 percent, you may redirect new investments toward debt or safer assets.
Do not confuse investing with trading. Trading focuses on short-term price moves, while investing focuses on business growth, earnings, ownership, and time. If you are tempted by quick trades, first understand the difference between trading and investing.
Frequent buying and selling also creates taxes, transaction costs, and emotional stress. A strong investment plan should reduce decisions, not create more of them.
Be Careful With High-Risk Opportunities
Indian investors often get attracted to low-priced shares, options trading, small-cap rallies, and unlisted shares. These products may have a place for experienced investors, but beginners should understand their risks before investing.
A low share price does not mean a stock is cheap. A ₹10 share can be more expensive than a ₹2,000 share if the underlying business has weak earnings, high debt, or poor governance. This is why you should know the reasons to stay away from penny stocks.
Unlisted shares are shares of companies that do not trade on NSE or BSE. Investors often buy them before a potential IPO, but these investments can have limited liquidity, uncertain pricing, wider spreads, and higher due diligence requirements. If you are exploring this space, first understand the risks of investing in unlisted shares in India and the legal aspects before investing in unlisted shares.
Avoid using borrowed money, emergency savings, or money needed for near-term goals in any risky investment. A good investor survives bad periods because they protect their financial base first.
Things to Keep in Mind
- Invest only surplus money: Keep your emergency fund, insurance premiums, rent, EMIs, and near-term expenses separate from your equity investments.
- Do not chase tips: A Telegram message or office tip is not research; understand the business, fund category, or ETF before investing.
- Respect your risk level: Small-cap funds and direct stocks can fall sharply, so invest only what you can hold through volatility.
- Avoid over-trading: Daily buying and selling often turns investing into an emotional activity and increases costs.
- Give goals enough time: Equity works best for long-term goals; do not depend on stocks for money you need within a few years.
- Track taxes and records: Maintain purchase details, capital gains records, and nomination information for every investment.
Frequently Asked Questions
How much money do I need to start investing in India?
You can start with as little as ₹500 or ₹1,000 per month through many mutual fund SIPs. The amount matters less than creating a habit and increasing investments as your income grows.
Is SIP in mutual funds better than direct stocks for beginners?
For many beginners, a SIP in a diversified mutual fund is easier because it provides diversification and professional fund management. Direct stocks need more research, monitoring, and emotional discipline.
Can I become a good investor without checking the market daily?
Yes. In fact, long-term investors usually benefit from checking less often. Review your portfolio periodically, but focus more on your goals, allocation, and investment discipline than daily prices.
Should I invest in large-cap, mid-cap, or small-cap funds?
Start with large-cap, flexi-cap, or index funds if you are new. Add mid-cap and small-cap exposure only after you understand that they can deliver higher volatility and deeper temporary losses.
Are ETFs good for beginner investing in India?
ETFs can work well for beginners because they offer diversification and trade on the NSE and BSE like shares. However, you need a Demat and trading account, and you should check liquidity and tracking quality before buying.
Should beginners invest in unlisted shares before an IPO?
Most beginners should avoid making unlisted shares a core investment. They carry liquidity, valuation, transfer, and due diligence risks that make them harder to manage than listed stocks or mutual funds.
Becoming a good investor means setting clear goals, choosing understandable products, investing consistently, diversifying wisely, and avoiding emotional decisions. Start simple, stay consistent, focus on the long term, and let your process—not market noise—guide your decisions. I hope you found this article helpful.
You May Also Like
- How to maintain discipline in the stock market
- Long-term investment strategies for Indian investors
- How to avoid losing money in the stock market
- Best mid-cap mutual funds for long-term investing
- Can beginners make money in the stock market?
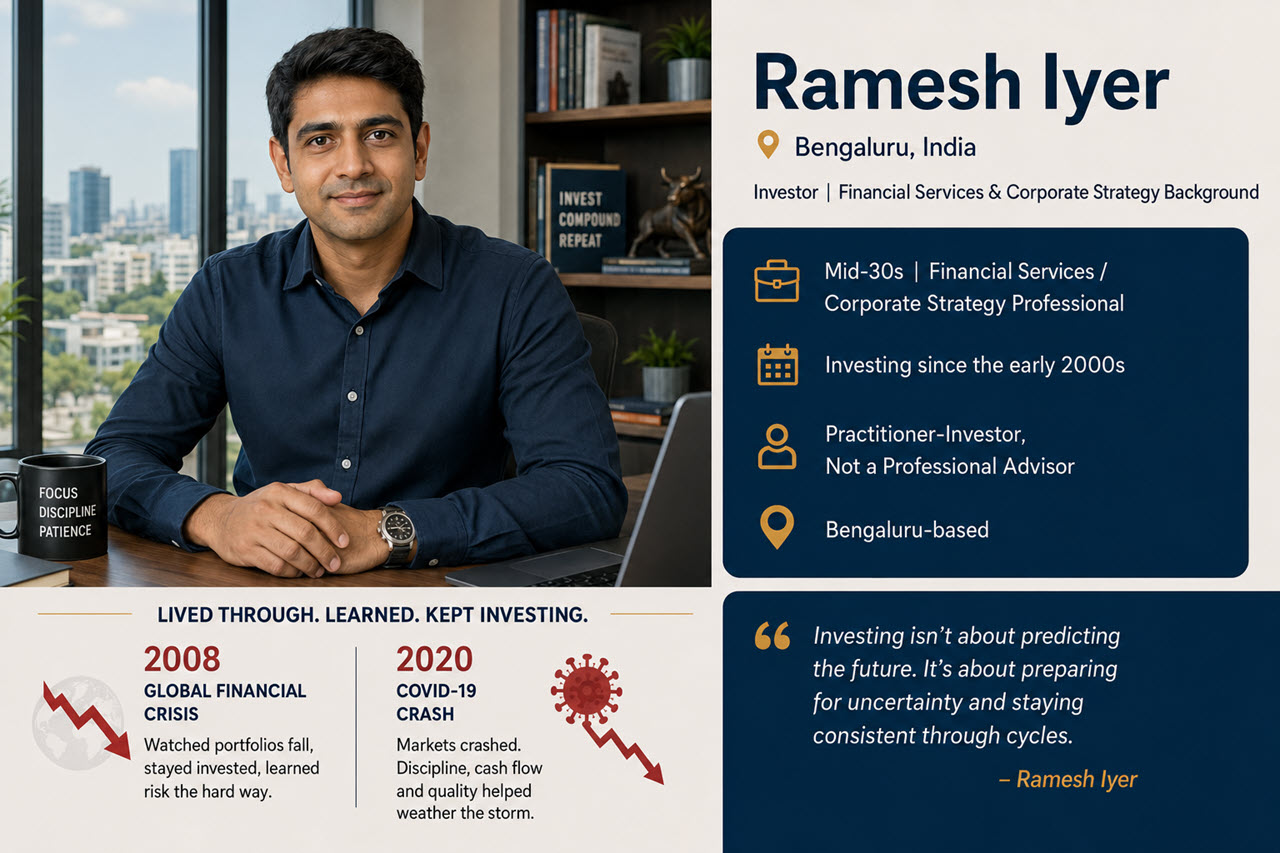
Ramesh Iyer is the founder of StocksInfo.AI, a Bengaluru-based investor with two decades of market experience, writing plain-language content on stocks, mutual funds, and ETFs for everyday Indian investors. Read more